IMF Warns of Regional Contraction as Geopolitical Tensions Weigh on Middle East Growth
هشدار صندوق بینالمللی پول درباره رکود منطقهای؛ سایه جنگ بر اقتصاد خاورمیانه در سال ۲۰۲۶
The International Monetary Fund predicts a significant economic contraction for Middle Eastern nations in 2026 due to ongoing regional conflict. Meanwhile, Iranian officials claim US diplomatic failure as Tehran hosts national health events amid domestic price stability.
At time of publishing
USD
260,400
Toman
Gold 18K
25.81M
Toman / gram
Bitcoin
$83,649
US Dollar
Tether
255,913
Toman
The IMF’s Grim Forecast for the Middle East
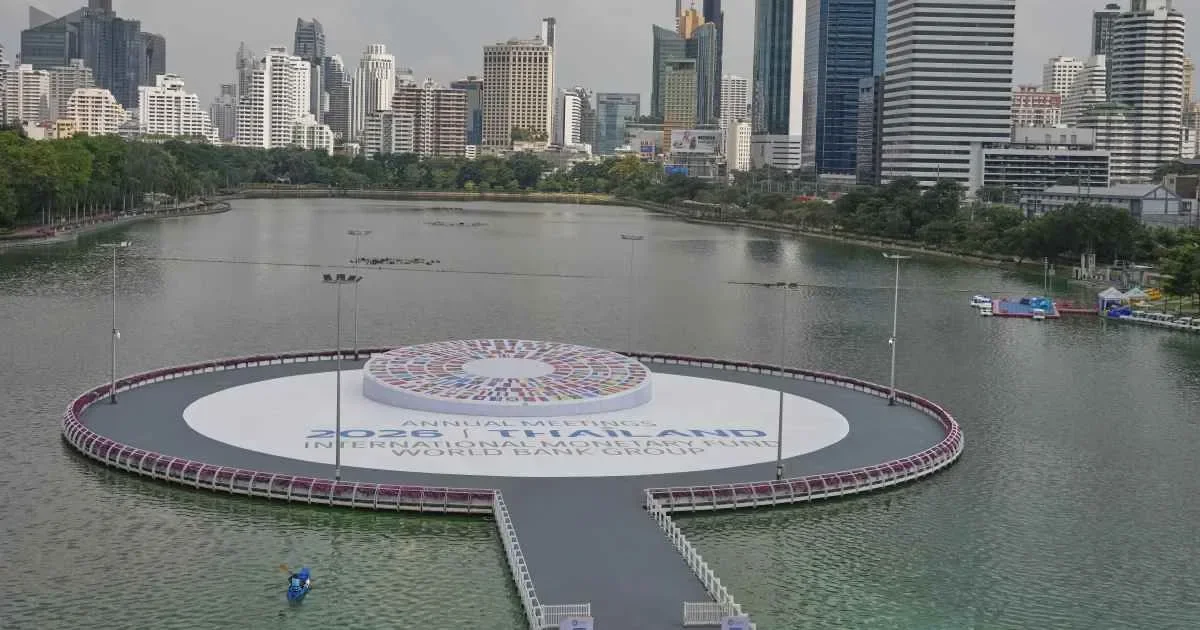
The International Monetary Fund (IMF) has issued a sobering update from Bahrain, projecting that the economies of the Middle East and Central Asia are set to shrink significantly throughout 2026. This contraction is primarily attributed to the spillover effects of the ongoing conflict involving the United States, Israel, and Iran. According to the report, major regional players including Iraq, Bahrain, Kuwait, and Qatar are facing double-digit declines in their Gross Domestic Product (GDP). The disruption of trade routes and the heightening of risk premiums have made it increasingly difficult for these nations to maintain their growth trajectories, signaling a period of prolonged austerity for the region.
For the Iranian reader, this macro-economic shift is already reflected in the local currency markets. On Tuesday, October 13, 2026, the USD sell rate moved from 260,600 to 260,400 Toman, a marginal decrease of 0.1%. While the currency remains relatively stable in the immediate term, the IMF's forecast suggests that regional trade barriers and reduced foreign investment could lead to intensified pressure on the Toman in the coming months. As oil-dependent neighbors face GDP declines, the interconnected nature of regional finance means that Iran's own economic recovery remains precariously tied to the de-escalation of military tensions.
Rhetoric vs. Reality: Tehran’s Diplomatic Stance
Amidst these economic warnings, Iranian Parliament Deputy Speaker Hamidreza Haji Babai has publicly claimed that the United States has failed to rally its traditional allies in the ongoing regional confrontation. Speaking to state media, Babai argued that Washington’s strategy to isolate Tehran has backfired, leaving the US increasingly alone in its military posturing. This narrative of "Western failure" is a staple of state communication, aimed at bolstering domestic confidence even as the IMF points to a fracturing regional economy. However, the reality of diplomatic isolation remains a complex hurdle for Iran’s trade aspirations, especially as sanctions continue to limit access to global banking systems.
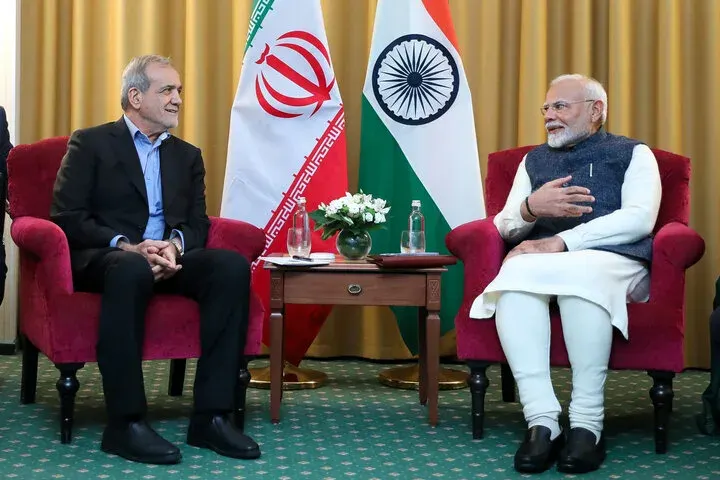
Simultaneously, the Iranian leadership is attempting to project a sense of internal normalcy and social cohesion. President Masoud Pezeshkian and Health Minister Mohammad-Reza Zafarghandi recently attended a national health and community event in Tehran, focusing on mosque-centered community health initiatives. While the government emphasizes these social programs, the economic data suggests a disconnect between official ceremonies and the underlying financial strain. The Emami coin remains static at 264,500,000 Toman, but gold 18k has seen a slight dip of 0.4%, moving from 25,919,940 to 25,809,132 Toman per gram, reflecting a cautious wait-and-see approach from local investors.
The K-Shaped Global Recovery and Resource Wars
Beyond the Middle East, the global economy is increasingly being described as "K-shaped," a term highlighting the growing divide between winners and losers. The IMF notes that countries heavily exposed to oil shocks are struggling, while those benefiting from the surge in Artificial Intelligence (AI) demand are pulling ahead. This divergence is causing a shift in global power dynamics, as seen in the renewed interest in the Panguna copper mine in Bougainville. The mine, which led to a civil war decades ago, is now being reconsidered for reopening due to the global hunger for copper—a critical component in green technology and electronics. This "resource nationalism" mirrors the tensions seen in the Middle East, where control over energy and minerals often dictates geopolitical alliances.
Adding to the global sense of economic friction, businesses in Australia are reportedly using a recent ban on credit card surcharges as a "cover" to implement even larger price increases. Experts suggest that instead of passing on the 1.5% savings to consumers, businesses are rounding up prices, effectively fueling inflation under the guise of regulatory compliance. This pattern of hidden inflation is a global phenomenon that Iranian consumers know all too well. As the world navigates these complex shifts, from AI breakthroughs to resource-driven conflicts, the volatility in global gold prices—currently at 4,187.30 USD per ounce—remains the primary indicator of universal economic anxiety.
Frequently Asked Questions
Why is the IMF predicting an economic contraction for the Middle East in 2026?
What was the direction of the USD/IRR exchange rate today?
How is the 'K-shaped' recovery affecting global markets?
Understanding the K‑Shaped Recovery: Why the Middle East May Diverge
The term K‑shaped recovery describes a post‑crisis economic trajectory in which different sectors, regions, or income groups experience markedly divergent paths—some surge ahead while others lag or even contract. Visually, the graph resembles the letter "K", with one arm pointing up (growth) and the other pointing down (decline). This pattern contrasts with the more familiar "V" or "U" recoveries, where the whole economy eventually rebounds in a more uniform way.
The International Monetary Fund (IMF) has applied the K‑shaped lens to the Middle East, warning that geopolitical tensions, sanctions, and uneven commodity price shocks could push the region into a split recovery. Oil‑exporting countries that can maintain production and benefit from high oil prices may see robust growth, while economies reliant on tourism, trade, or foreign investment—such as Iran, Lebanon, and parts of North Africa—could face stagnation or contraction. The IMF’s 2024 regional outlook highlights this divergence, noting that policy uncertainty and currency pressures (e.g., the USD/IRR exchange rate) exacerbate the split.
For investors and policymakers, recognizing a K‑shaped dynamic matters because it shapes where capital flows and which policy tools are effective. In booming sectors, governments may focus on managing inflation and overheating, while lagging parts may need targeted fiscal support, structural reforms, or debt relief. The split also influences asset prices: a weaker Iranian rial and rising gold prices in Tehran reflect safe‑haven demand amid uncertainty, whereas copper projects like the Bougainville mine may attract financing if global commodity demand stays strong.
Ultimately, a K‑shaped outlook underscores that a single macro‑indicator—like regional GDP growth—can mask deep internal disparities. By tracking sector‑specific data, exchange‑rate movements, and geopolitical developments, analysts can better anticipate which economies will climb the upward arm of the "K" and which will need assistance to avoid a prolonged downturn.